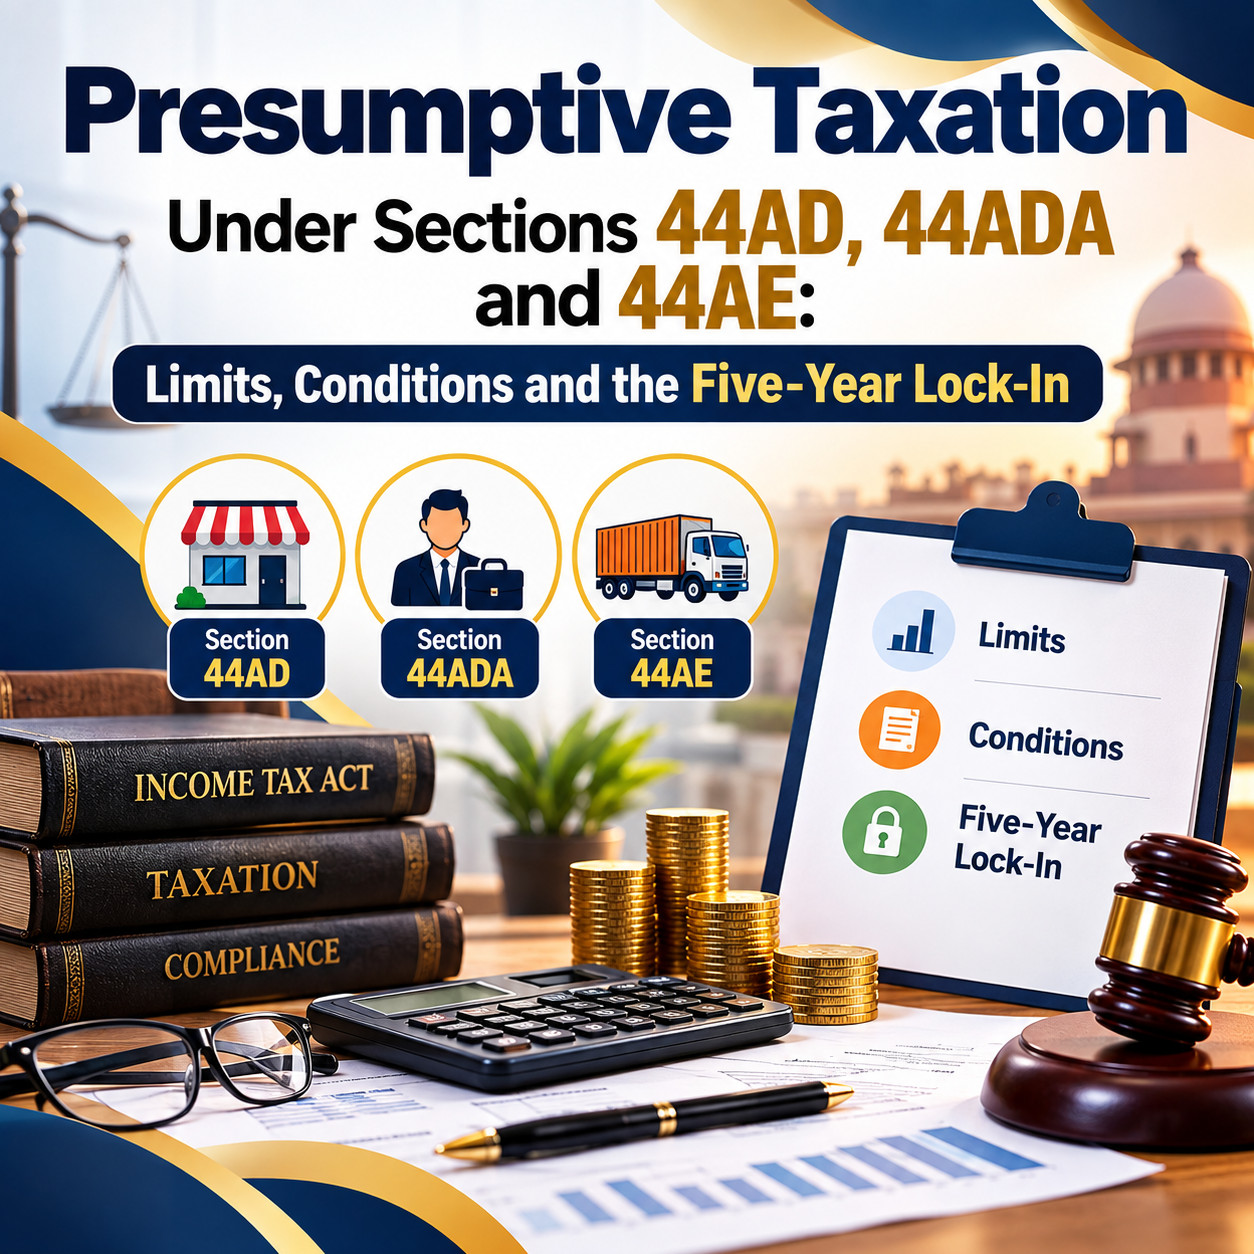


Presumptive Taxation Under Sections 44AD, 44ADA and 44AE: Limits, Conditions and the Five-Year Lock-In
Presumptive taxation is an important income-tax compliance framework for certain small businesses, specified professionals and transport operators. Instead of calculating taxable profit after recording every individual business expense, eligible taxpayers can declare income according to prescribed rules under Sections 44AD, 44ADA and 44AE of the Income-tax Act.
The purpose of these provisions is to simplify tax compliance for eligible taxpayers and reduce the burden associated with maintaining detailed books and determining actual business profits. However, each scheme has different eligibility requirements, income calculation rules and conditions.
For taxpayers considering presumptive taxation under Sections 44AD, 44ADA and 44AE, understanding the applicable limits and the consequences of leaving the scheme is particularly important.
What Is Presumptive Taxation?
Under the presumptive taxation system, income is calculated on a prescribed basis instead of requiring the taxpayer to determine taxable business or professional profit through the usual detailed computation.
The three commonly used provisions are:
Section 44AD – eligible businesses
Section 44ADA – specified professions
Section 44AE – business of plying, hiring or leasing goods carriages
The Income Tax Department continues to list these provisions as simplified methods for eligible taxpayers.
Section 44AD: Presumptive Taxation for Eligible Businesses
Section 44AD generally applies to a resident individual, resident Hindu Undivided Family (HUF), or resident partnership firm other than an LLP carrying on an eligible business, subject to the statutory conditions.
The standard turnover threshold is ₹2 crore. However, this limit increases to ₹3 crore where cash receipts during the previous year do not exceed 5% of total turnover or gross receipts.
The presumptive income is generally:
8% of eligible turnover or gross receipts; and
6% for qualifying receipts received through specified banking or electronic modes.
A taxpayer may also declare a higher amount where the actual income is higher.
Certain businesses are excluded from Section 44AD, including specified agency businesses, commission or brokerage income and businesses covered by Section 44AE. Therefore, simply having turnover below the threshold does not automatically establish eligibility.
Section 44ADA: Presumptive Taxation for Professionals
Section 44ADA is designed for resident individuals and partnership firms other than LLPs carrying on specified professions referred to under Section 44AA(1).
Examples of specified professions include legal, medical, engineering, architectural, accountancy and technical consultancy professions.
The normal gross-receipts threshold is ₹50 lakh. Where cash receipts do not exceed 5% of total gross receipts, the threshold can increase to ₹75 lakh.
Under the scheme, 50% of the gross professional receipts is generally treated as presumptive professional income. A professional can declare a higher amount if the actual income is higher.
Where a taxpayer claims income lower than the prescribed 50% and the applicable total-income condition is satisfied, the law can require maintenance of books and a tax audit under the relevant provisions.
Section 44AE: Presumptive Taxation for Transport Businesses
Section 44AE applies to a person engaged in the business of plying, hiring or leasing goods carriages who does not own more than 10 goods carriages at any time during the previous year.
Unlike Sections 44AD and 44ADA, Section 44AE does not use a turnover-based threshold. Instead, income is determined according to the prescribed vehicle-based calculation.
For a heavy goods vehicle, presumptive income is ₹1,000 per ton of gross vehicle weight for every month or part of a month during which the vehicle is owned. For other goods vehicles, the prescribed amount is ₹7,500 per month or part of a month. A heavy goods vehicle generally means a goods carriage with gross vehicle weight exceeding 12,000 kilograms.
The Five-Year Lock-In Under Section 44AD
One of the most important aspects of presumptive taxation is the five-year restriction under Section 44AD.
If an eligible taxpayer declares income under Section 44AD and, during the specified following period, declares profit otherwise than in accordance with the presumptive provisions, the taxpayer can become ineligible to claim the Section 44AD benefit for five assessment years following the assessment year in which the deviation occurs.
This is sometimes described as a five-year lock-in, although technically it operates as a restriction on re-entering the presumptive scheme after the prescribed circumstances arise.
Therefore, choosing Section 44AD should not be viewed merely as a year-to-year tax calculation. Businesses should consider whether they expect to remain within the scheme and whether their future profit reporting may require a different method.
Important Conditions Before Choosing Presumptive Taxation
Before opting for presumptive taxation, taxpayers should consider:
Whether they fall within the eligible taxpayer category.
Whether their business or profession is covered by the relevant section.
Whether turnover or gross-receipt limits are satisfied.
Whether cash-receipt conditions affect the higher threshold.
Whether they have income from excluded activities.
Whether they may need to declare lower profits.
Whether the Section 44AD five-year restriction could become relevant.
Whether their return form and other compliance requirements are applicable.
The Income Tax Department also notes that presumptive taxation under these provisions is subject to specific conditions rather than being available automatically to every small taxpayer.
Presumptive Taxation and Compliance Planning
Presumptive taxation can simplify income computation, but taxpayers should still maintain reliable records of turnover, receipts, invoices, bank transactions and other relevant financial information.
The availability of a presumptive scheme does not mean that every other tax obligation disappears. Businesses and professionals should separately consider requirements relating to GST, TDS, advance tax, return filing and other applicable laws.
For 2026 tax compliance, taxpayers should also check the latest provisions, notifications and Income Tax Department guidance before filing because statutory thresholds and procedural requirements can be amended.
Conclusion
Presumptive Taxation under Sections 44AD, 44ADA and 44AE provides simplified methods for determining taxable business or professional income for eligible taxpayers. Section 44AD focuses on eligible businesses, Section 44ADA covers specified professionals, while Section 44AE applies to qualifying goods-carriage businesses.
The ₹3 crore threshold under Section 44AD, ₹75 lakh threshold under Section 44ADA subject to the cash-receipt condition, and the 10-vehicle condition under Section 44AE are important points to understand. Equally important is the five-assessment-year restriction associated with Section 44AD when the prescribed conditions for continuing under the scheme are not followed.
This article is intended solely for general information, tax updates and knowledge. The applicability of presumptive taxation depends on the taxpayer's facts, business or profession and the provisions applicable for the relevant tax year. Readers should verify the latest Income Tax Department guidance, Act, Rules and notifications before taking a tax position.
(https://taxationlegaladvisor.i....n/presumptive-taxati